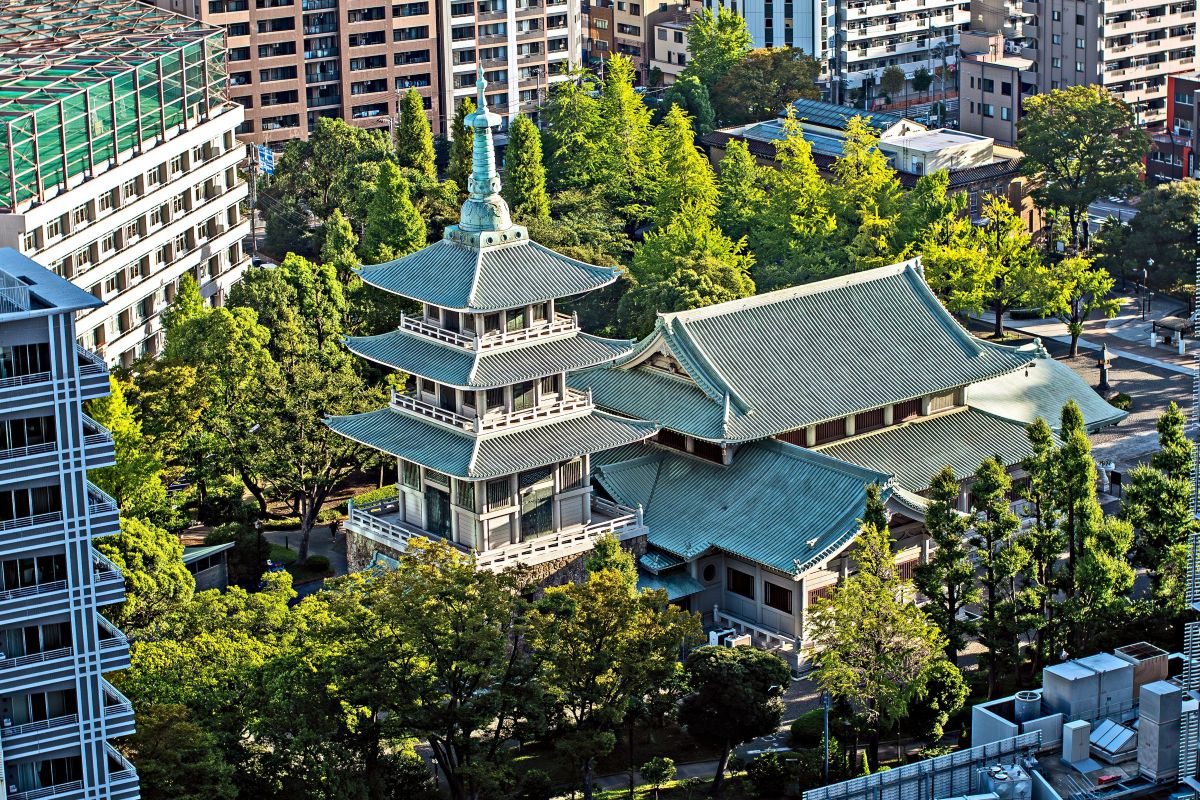
There are strong compelling reasons for developing data centers outside of the traditional hubs of Tokyo and Osaka regions.
The growth of data centers in Japan is highly concentrated in two regions – Greater Tokyo and Greater Osaka – together accounting for 90 per cent of data centre locations. Ironically, these two megaregions represent less than 10 per cent of the country’s land area, 40 per cent of the population, and half of the country’s total GDP of US$ 4.87 trillion.
Such hyper geographical concentration would have had catastrophic consequences if an earthquake happened. In seismic-prone Japan, such large-scale natural disasters are foreseeable risks. Hence, a diversification strategy away from those megacities is a natural step towards protecting and providing redundancies for these critical infrastructure.
Earthquakes and consequently higher seismic engineering premiums especially in densely populated megacities are just two risks that immediately come to mind – there are other equally compelling reasons for the move towards suburban corridors. Key among them are high capital investment required in Tokyo and Osaka compared to other regions in Japan. Land prices are much higher and availability is very limited in those two cities. According to a Mordor Intelligence report, average land prices in central Tokyo rose by an astounding 69 per cent in 2024, significantly raising the cost of development.
Also in densely built areas within the megaregions, large scale expansions are not practical. Japan has been ranked eighth globally on Cloudscene for data center density based on a population of 125.5 million.
Some areas also experience power supply constraints thus limiting buildouts.
The case for developing data centers in suburban areas gets even stronger when one takes into account community pushbacks. As with the rest of the data center hubs around the world especially in the US and Europe, community resistance is becoming a real risk. For example, the local community in Koto ward (Eastern Tokyo) was up in arms against data centers, according to Mordor report. This has pushed operators to develop in suburban areas like Inzai City which has rolled out the red carpet to data centers granting them municipal incentives. Inzai also has the advantage of having larger plots of land available for data centers. The number of data centers in the city now stands at 10, which is the largest after Tokyo and Osaka.
The other push factors towards a suburban setup is the extraordinary long wait time for grid connection approvals. Tokyo Electric Power Company reports a queue time of more than 36 months for over 10MW connections. As utilities balance renewable-generation integration with load growth, operators are resorting to paying extra upfront to secure provisional slots in the interim period.
Some developers have tried to solve this problem by installing on-site gas turbines and lithium-ion storage while waiting for utility supply but this only adds a layer of complexity and risk to the project.
Government Initiatives
Acknowledging this, the government is actively promoting regional diversification of data centers.
Since 2021, the government has extended various types of assistance to companies developing data centers outside of the two mega regions and other metropolitan areas. The assistance includes resilience strengthening measures and communication efficiency. The government has also come up with initiatives such as “Regional Revitalization” and “Digital Infrastructure Development Plan 2030”, to promote regional diversification while also encouraging the decarbonisation of data centers.
Part of the initiatives include data center development through Watt-Bit collaboration where regional diversification is promoted through collaboration of power and telecommunications.
The government also hopes to create five or more data center hubs to enhance GX-driven industrial growth while regional DX promotion including AI utilisation is also encouraged.
The other policy relies on advanced technology to achieve low latency inter-data center connections using All Photonic Network technology by 2030 and advanced computing resource power load control by 2035. Lower latency and better connection would encourage data center development outside of the densely populated megaregions.
Emerging DC clusters
One of the major players developing data centers outside of traditional hubs is SoftBank Group which is said to have identified Sakai City and Toyama as potential hubs for massive AI data centers and superclusters. Toyama (Nanto Campus) is emerging as a massive digital infrastructure hub due to its abundant power supplies (about 3.1GW) and its strategic location being part of an economic triangle with Tokyo and Osaka. One of the companies developing large-scale AI data centers there is Gigastream Toyama.
Hokkaido and Kyushu have also emerged as popular new data center clusters. Hokkaido (Sapporo and Ishikari) has the advantage of a cool climate supporting free air-cooling. Ishikari hosts major facilities, including Rakuten Ishikari data center and White Data Center (WDC) which makes use of winter snow for cooling.
Meanwhile, Kyushu, the most southerly island of Japan, stands out due to its many advantages such as abundant and affordable renewable energy, easy availability of land and power, direct submarine cable connections and its proximity to Shanghai and Seoul. The island has even been positioned as the data center gateway to East Asia.
As a result, hyperscalers and AI operators are rushing in to build, contributing to 88 per cent of all planned projects being self-built. Cumulative supply has risen exponentially from just 101 MW in 2023 to about 3 GW by Q2 2026, according to research firm DC Byte.
The island hosts some of the largest data centers in Japan, for example, IDC Frontier Asian Frontier and Telehouse Fukuoka, as well as Asia-Pacific Land’s upcoming Kitakyushu Data Center Campus, sited on 15.5 acres of land; and the US$ 2 billion Itoshima Campus, which aims to expand up to 150MW capacity.
Okinawa is an important landing point for submarine cables connecting Japan to North America and mainland Asia. Nagoya, an important industrial and manufacturing hub, meanwhile attracts data centers like KDDI/Telehouse and major network exchange hubs serving the Tokai and Kinki districts.
The subsidised 15MW AI data center in Fukushima is a clear example of the government’s commitment to distribute critical digital infrastructure nationwide.
According to Data Center Map Japan directory, as of early June, there are a total of 256 data centers in Japan run by 73 operators. Out of that, 105 are in Tokyo and 55 in Osaka. This is followed by 10 in Inzai City, 9 in Yokohama, 8 in Sapporo and 6 each in Nagoya, Fukuoka and Kanazawa, 5 in Kawasaki, 4 each in Tsukuba, Naha, and Takamatsu, and between 1 – 3 in a few other locations.
Massive room for growth
Clearly, there is still a lot of room for growth in regions outside of Tokyo and Osaka. With compelling pull factors such as abundant renewable energy, lower costs, proximity to Tokyo and Osaka, or to manufacturing hubs, direct submarine cable connections and even free snow cooling, on the back of strong government support, it is only a matter of time before data center developers realise the advantages and start beating a path there.
However, relocating to suburban areas is not all smooth sailing. While land prices might be cheaper, the developer would have to fork out extra to invest in dark fiber routes and redundant substations. This will extend project timelines and costs thus affecting the overall data center supply market in Japan.
Still, data centers in non-traditional locations are perfect for edge and disaster-recovery workloads. More importantly, they possess a host of advantages as outlined earlier that their counterparts in the megacities do not have.
*This article has previously appeared in Issue 13 of cloud & datacenters magazine.